AMD reported third-quarter 2026 revenue of $13.377 billion, up 45% from a year earlier, as Data Center sales almost doubled. Its November 3 release in Santa Clara forecasts roughly $17 billion of fourth-quarter revenue, plus or minus 3%, with a non-GAAP gross margin of about 55%.
The results, for the quarter ended September 26, put a stronger data-centre business alongside a weaker combined Client and Gaming segment. That split matters to readers assessing the earnings announcement: the headline growth reflects a changing sales mix, while the much larger fourth-quarter number still depends on future deliveries.
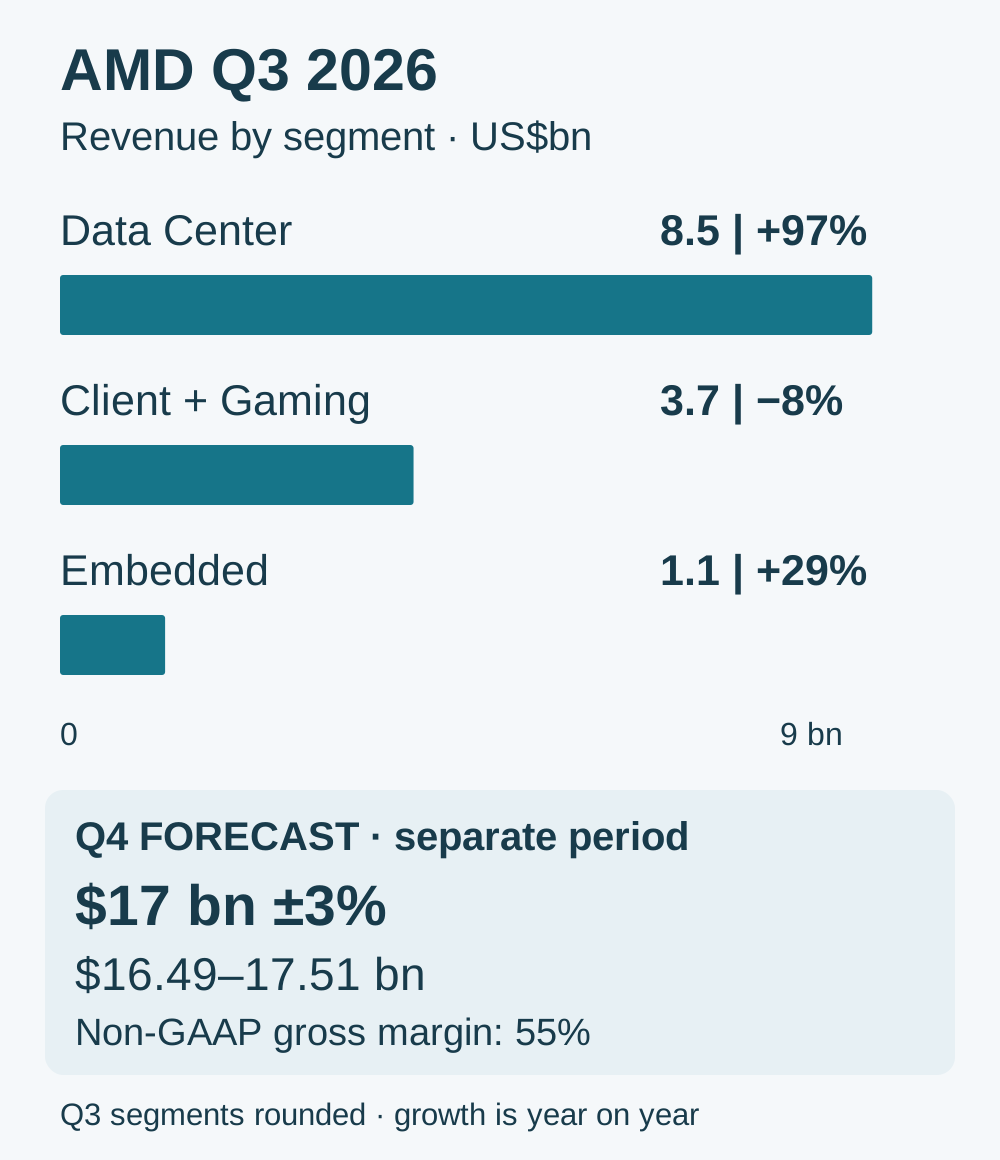
Data Center drives growth; consumer businesses diverge
Data Center revenue reached $8.5 billion, up 97% year over year. AMD attributed the increase to demand for EPYC server processors and the launch of Instinct MI450-series GPUs. At the reported rounded segment value, Data Center accounted for about 64% of total revenue: 8.5 divided by 13.377 is approximately 63.5%.
The combined Client and Gaming segment generated $3.7 billion, down 8%. Within it, Client revenue rose 7% to $2.9 billion, while Gaming fell 40% to $773 million as semi-custom and graphics revenue declined. Embedded revenue grew 29% to $1.1 billion, so the record total did not involve uniform growth across product lines.
Two earnings measures describe the same quarter
AMD reported GAAP net income of $2.428 billion and diluted earnings per share of $1.46. Its adjusted figures were $3.471 billion and $2.09 per share. The company’s reconciliation includes stock compensation, acquisition-related intangible amortisation and other adjustments; the adjusted figure should be compared with an estimate on the same accounting basis.
The distinction also applies to margins. Third-quarter gross margin was 54% under GAAP and 56% on the adjusted basis. The fourth-quarter 55% forecast is non-GAAP. Putting those labels beside the numbers makes it possible to follow changes without treating unlike measures as a single continuous series.
The Q4 range sets the next test
Three per cent of $17 billion is $510 million, giving an implied revenue range of $16.49 billion to $17.51 billion. AMD says the midpoint would represent approximately 66% annual growth and 27% sequential growth. Readers can use the official results and reconciliation to compare subsequent reported sales and margins with those two guidance measures.
The record quarter establishes that Data Center is now the principal contributor to AMD’s reported sales. Sustaining the projected step-up requires the supply and delivery assumptions behind its outlook to hold: AMD names component availability, manufacturing capacity and export restrictions among the risks. The next earnings report will test the revenue range and margin together; this release does not establish a future share price.
Prepared by the editorial team from official records and reviewed public reporting.
AI assisted with drafting and editing. This article is part of our preview edition. Editorial standards & corrections →